
5 Deal-Killers in Apartment Buildings for Sale in New Jersey

The market for an apartment building for sale in New Jersey keeps drawing attention for a reason. Demand stays strong, the state sits close to New York City and Philadelphia, and well-bought multifamily assets can still produce solid returns.
But a property that looks like a cash machine on paper can turn into a problem fast if the underwriting is loose. In New Jersey, the risks are often local, technical, and easy to miss. The goal here is simple: protect capital by spotting five deal-killers that can sink a multifamily purchase before the first rent check clears.
Top Multifamily Red Flags in Apartment Buildings for Sale in New Jersey
Successful due diligence has to go beyond fresh paint and tidy photos. A serious buyer needs to check the rules and the real numbers behind the deal. This matters even more in a state where rent rules, inspection rules, taxes, and operating costs can shift the outcome fast.
-
Non-Compliance with Local Rent Control Ordinances
New Jersey does not run on one simple statewide rent-control rule. In practice, rent control is municipal, and the details change from city to city. Newark’s rent ordinance regulates certain residential units and requires registration, while Jersey City enforces its own rent control ordinance, and Hoboken has a separate rent leveling office and board.
That is where buyers get hurt. If you assume you can raise rents to market immediately after closing, you can crush the projected NOI before the property even stabilizes. A building that looks under-rented may actually be legally pinned to a much lower baseline.
-
Unresolved “Green Card” / DCA Code Violations
Another common trap is buying a building with unresolved New Jersey Department of Community Affairs issues. The Bureau of Housing Inspection oversees hotels and multiple dwellings with three or more units, and the state requires cyclical inspections. Official DCA guidance confirms that these inspections are part of the state’s enforcement system for housing and fire-safety rules.
If a seller leaves behind violations, the new owner may inherit more than paperwork. Code problems can mean fire-safety repairs, structural fixes, and other unplanned CapEx that land right after closing. That kind of surprise can stall operations and drain reserves quickly.
-
Deferred CapEx Against Older Building Envelopes
A lot of New Jersey multifamily stock is old. In places like Hudson and Essex counties, you still see century-old brick buildings, aging mechanics, and systems that have been patched for years. This history can be charming for tenants, but it is brutal for an owner who did not budget honestly.
The usual trouble spots are easy to name: cast-iron plumbing that is near the end of its life, outdated electrical wiring, master-metered heat that has not been separated, and roofs that are already past their best years. Add in HVAC overhauls or utility separation work, and the value-add story can disappear fast.
-
Inflated Pro-Formas and Misrepresented Expense Ratios
This is the classic broker-fluff trap. A property is marketed with a polished pro forma, but the actual trailing 12-month numbers tell a very different story. Gross rent, management fee, maintenance reserve, insurance, property taxes, vacancy reserve, utilities, and miscellaneous expenses need to be tested line by line.
In New Jersey, the blind spots usually show up in insurance and utilities. Premiums can rise fast, and water and sewer charges can hit harder than expected. This is why buyers should lean on T-12s, not just the seller’s story.
-
The Post-Sale Property Tax Assessment Shock
New Jersey property taxes deserve their reputation. State tax guidance says real property is assessed at true value, and county boards can order revaluations and reassessments to keep assessments equitable. This means the tax bill after a sale can look very different from the seller’s old bill.
This is the tax shock. A buyer closes, the county or municipality reviews the asset, and the assessment resets closer to the new purchase price or true market value. If the deal was underwritten on the seller’s historical tax bill, the numbers can fall apart fast. A positive-cash-flow asset can become negative overnight.
Navigate the New Jersey Multifamily Market with Confidence
New Jersey still offers strong multifamily upside, but only for buyers who stay disciplined. The real opportunity comes from balancing demand in the right submarkets with careful review of ordinances, inspections, building systems, expenses, and taxes. Miss any one of those, and a promising apartment building for sale in New Jersey can turn into a costly lesson.
Ready to start analyzing verified inventory and uncovering your next profitable investment? Browse vetted commercial listings, evaluate accurate cap rates, and filter the top apartment buildings for sale in New Jersey directly through the Apartment Buildings Portal.
Other News
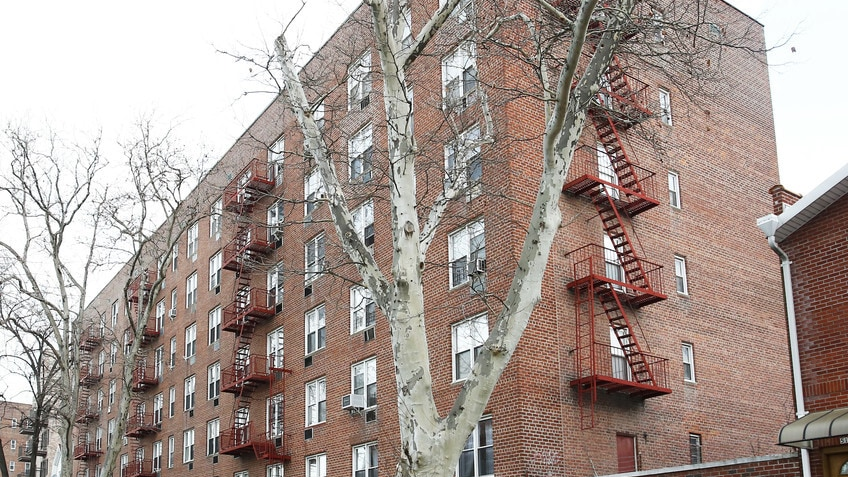
CBRE Arranges Financing for Rent-Stabilized Midwood Multifamily
CBRE originated a $15-million loan for a 175-unit rent-stabilized multifamily property located at 430 and 499 E. 8th St. in the Midwood section of Brooklyn. The financing was secured on behalf of ARM Management through Four Leaf Credit Union. The CBRE Capital Markets team of Judah Hammer, Jeff Feldman and Jack Hayes arranged the refinancing...
Learn more
Davis Provides $44M Construction Financing for Downtown Residential Conversion
JLL Capital Markets has arranged $44 million in financing for 31 Milk St., an adaptive reuse multifamily redevelopment in Downtown Boston. Managing director Anthony Cutone, director Madeline Joyce and associates Michael Schwarze and Joe Marinaro represented the borrower, Dinosaur Capital Partners and Mugar Enterprises. The three-year, senior construction loan was provided by an affiliate of...
Learn more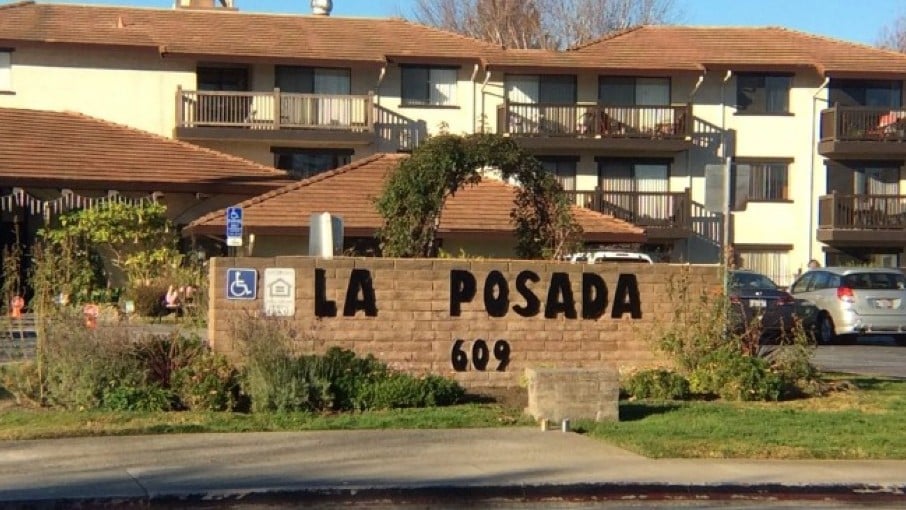
Jonathan Rose Makes Second Acquisition in Santa Cruz
Jonathan Rose Companies has acquired La Posada Apartments, a 150-unit, mixed-income community located at 609 Frederick St. in Santa Cruz. The $85-million transaction marks the ninth acquisition for the Rose Affordable Housing Preservation Fund VI and the firm’s second property in Santa Cruz. In line with its longstanding mission to preserve existing affordable housing, Jonathan Rose Companies acquired the property...
Learn more
Brokers
View All-
Remax Professionals
Re/Max Real Estate Professionals | New York
-
Jared Ennis
Central CA Commercial | California
-
Rick Recckio
Recckio Real Estate & Development
-
Eamonn McConnell
Avison Young - CA - ON - Greater Toronto
Lenders
View AllManagement
View All-
Essex Property Trust, Inc.
California
-
Josh A
California
-
Bob Tuteur
-
Andrew Schildcrout