
Data, Economics and Commercial Real Estate

The Gross Domestic Product (GDP) expanded by 4.3% during Q3 2025. At the same time, personal income experienced a 0.4% increase, while International Trade in Goods and Services and Q2’s International Transactions fell by $52.8 billion and $251.3 billion, respectively.
“Gains to real gross domestic product were driven by greater consumer spending, particularly on nondurable goods and services, as well as increased government outlays and a rise in net exports,” according to Marcus & Millichap’s “Gross Domestic Product” brief.
However, the above actions took place before the Oct. 1 to Nov. 12 government shutdown, resulting in delayed economic data and a negative impact on GDP growth.
Specifically, Q3 GDP momentum will likely not carry over into Q4, “given the impact of the federal government shutdown and the slight drop in private domestic investment,” the Marcus & Millichap brief noted. The brief’s authors forecast that GDP will expand by approximately 2% for the 2025 calendar year.
The other issue is the labor market. Marcus & Millichap’s “Economic Update” brief explained that “payroll gains remained modest in the private sector in October and November, while government employment fell mainly due to earlier layoffs showing up as severance periods expired.”
On the inflation side, November’s core CPI increased by 2.6% year over year, which was a positive. Still, the brief explained that data gaps resulting from the government shutdown might have led to an understatement of inflation. Furthermore, “if inflation moves higher again amid softer hiring, household budgets may face renewed pressure,” though “lower borrowing costs and fiscal support could, nevertheless, help stabilize activity.”
Here’s how this might impact commercial real estate’s four “major flavors.”
Multifamily: A Mixed Bag
Barriers to homeownership remain high, especially in the face of lower supply. The result is that many households are remaining in the renter pool, leading to lower vacancies that were “supported by fewer deliveries, with 2025’s completion total marking a three-year low,” according to the “Gross Domestic Product” brief.
At the same time, Marcus & Millichap’s “Economic Brief” explained multifamily’s bifurcation, in which “Class C concession usage climbed to near-record levels in November. Roughly 20 percent of these units now offer incentives, well above rates at higher-quality properties.”
Retail: Positioned for Possible Buying Decline
Vacancies remain low on the retail side “despite the net relinquishment of over 13 million square feet (of space) earlier this year,” according to the “Gross Domestic Product” write-up. Slowing construction activity supported backfilling.
Still, retailers could reduce expansion plans due to lower consumer confidence and continued uncertainty about U.S. trade policy. While total savings increased, “disposable personal income was unchanged in the third quarter, which could lead to less spending at stores and restaurants in the immediate future,” the brief noted.
Office: Building Momentum
The office sector has benefited from a dwindling pipeline and increased demand. Marcus & Millichap’s GDP brief said that top-tier, amenity-rich Class A properties in major metros continue to experience strong demand, while tenants “are generally favoring newer, smaller, suburban offices.”
The brief’s analysts anticipate a smaller construction pipeline for 2026, which could limit modern space options and possibly lead some tenants to updated, older stock.
Industrial: Ongoing Supply
While industrial deliveries are slowing, “completions have exceeded the long-term average in each of the past nine years,” according to the GDP brief. The extra supply has led to an increase in national vacancy.
But the brief explained that approximately half of the deliveries were limited to ten major markets, “allowing about a third of major metros to record third-quarter vacancy rates below the U.S. mark.”
Other News

Queens’ Tallest Tower Reaches 90% Leased, Adds First Retail Tenants
BLDG Management Co., Inc announced that The Orchard, Queens’ tallest tower, has surpassed 90% leased across its 824 residences nine months after launching residential leasing. The milestone occurs as the 70-story Long Island City development recently signed its first three retail tenants: K-beauty brand Tokimo, Japanese tea and beverage brand Mollytea and financial technology platform...
Learn more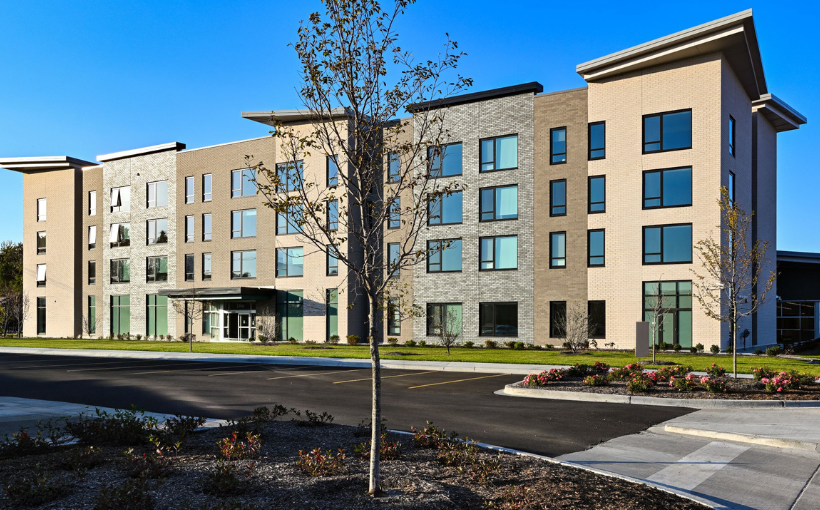
80-Unit Seniors Housing Development Opens in Suburban Chicago
Leyden Senior Apartments, a new four-story independent senior living development in Franklin Park, recently opened. Located at 2506 N. Mannheim Road, Leyden Senior Apartments offers one- and two-bedroom residences. The adjacent newly constructed Carl Fiorito Senior Center will be available to the entire community. Owned by Leyden Apartments LP, Leyden Senior Apartments was designed by...
Learn more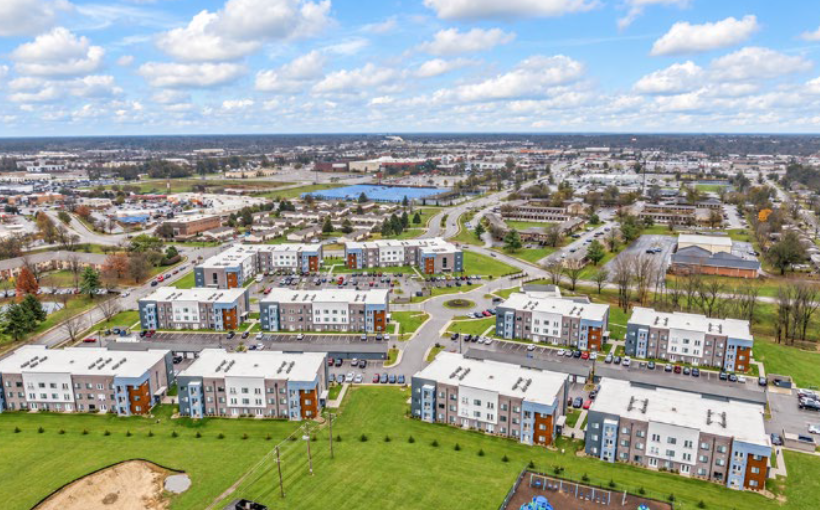
312-Unit Multifamily in Indiana Changes Hands
Northmarq’s Investment Sales team, led by Bobby Schiavone, Jordan Arand and Adam Klenk, led the sale of The Bend Apartments, a 312-unit garden apartment community located at 1909 Greentree Blvd. in Clarksville, Indiana. Northmarq represented the seller, a regional multifamily developer. The buyer was a private investor. “The Bend generated significant investor demand, further proving...
Learn more
Brokers
View All-
Remax Real Estate Professionals
Re/Max Real Estate Professionals
-
Jared Ennis
Central CA Commercial | California
-
Rick Recckio
Recckio Real Estate & Development
-
Greg Corbin
Northgate Real Estate Group
Lenders
View AllManagement
View All-
Essex Property Trust, Inc.
California
-
Josh A
California
-
Bob Tuteur
-
Andrew Schildcrout